Showing posts with label FIRE. Show all posts

Thursday, August 29, 2013

MB360: FIRE sector is back, big time

MB360 gives us great stats to illustrate starkly the so-called financialization of the U.S. economy: 

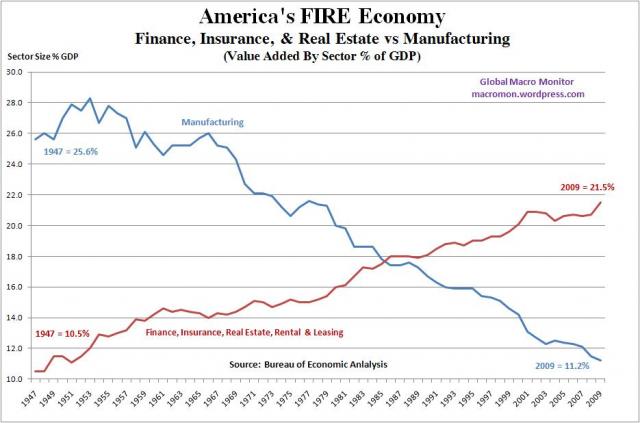
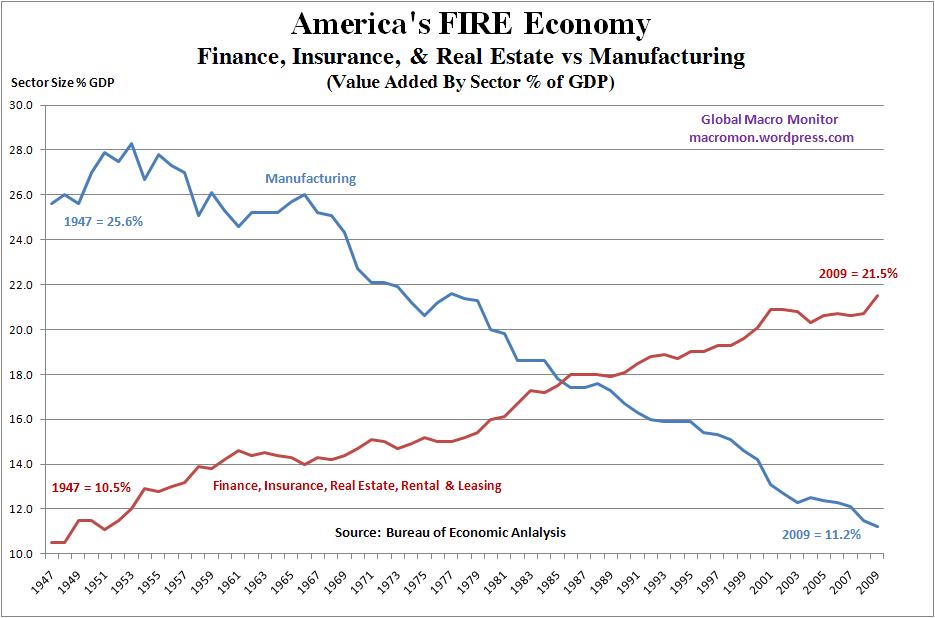
In 1947, the FIRE side of the economy made up roughly 10 percent of GDP. Today it is 21 percent.  On the other hand manufacturing in 1947 made up 25 percent of GDP while today it is closer to 11 percent.

Near-zero interest rates by the Fed and TBTF bank bailouts are direct federal government aid to the FIRE sector.  It's called socializing risk and privatizing rewards.  

Meanwhile, bizzaro conservatives assure us that if only Americans would stop being so lazy and collecting food stamps, then our economy would turn around. [Facepalm].  Foks, this is government-sponsored upward redistribution of wealth.  

If only the Tea Parties would brandish their pitchforks over the real redistribution problem in America!


Posted by mybudget360 
August 27, 2013

The current economy is juiced on the rivers of easy debt.  An addiction that is only getting worse.  Want to go to college?  You’ll very likely go into deep student debt given the rise in college tuition.  Want a home?  Prices are soaring because of speculation but you’ll need a bigger mortgage to buy.  Want a modest car? A basic new car that has four wheels will likely cost $20,000 after taxes after fees are included.  Need gas for that car?  The price of a gallon has quadrupled since 2000.  Combine this with the reality that half of Americans are living paycheck to paycheck and you can understand why the debt markets continue to grow at an unrelenting pace.  Here is some food for thought; in the last 10 years, GDP has gone up $5.2 trillion however, the total credit market has gone up by $24.5 trillion.  An increasingly large part of our economic growth is coming from massive leverage.  This is why the market sits fixated on the Fed’s next move regarding interest rates even though in context, rates are already tantalizingly low.  The FIRE economy is driving a large portion of corporate profits yet most Americans are left in the cold winds of austerity.

GDP being driven by FIRE

More and more of our growth is coming from a massive expansion of debt:
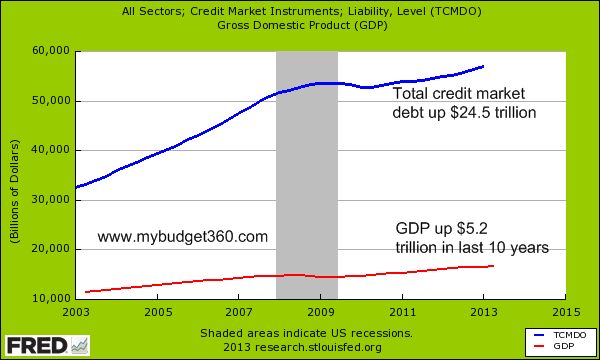
total credit market debt owed

The total credit market is now roughly 4 times the size of our annual GDP (inching closer to $60 trillion in the US).  While some think that this growth is natural and easy, in reality most of it is coming from growth in the financial services side of the economy.  The banking system is currently operating in a way that really does not benefit the typical Americans family.  Take a look at two employment sectors over the last few years:
fire-economy

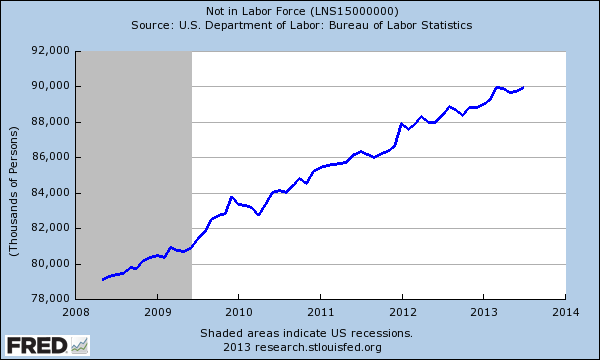
In 1947, the FIRE side of the economy made up roughly 10 percent of GDP.  Today it is 21 percent.  On the other hand manufacturing in 1947 made up 25 percent of GDP while today it is closer to 11 percent.  It comes as no surprise especially as we now see big banks and hedge funds crowding out the real estate trade.  Prices in real estate continue to rise at levels last seen during the bubble yet the homeownership rate continues to fall.  We keep adding more and more Americans as “non-workers” and then wonder why we have 47 million on food stamps:
not in labor force

The number of Americans not in the labor force is booming because of demographics but also because people are dropping out of the workforce.  This certainly doesn’t coincide with some of the data being produced from other channels.

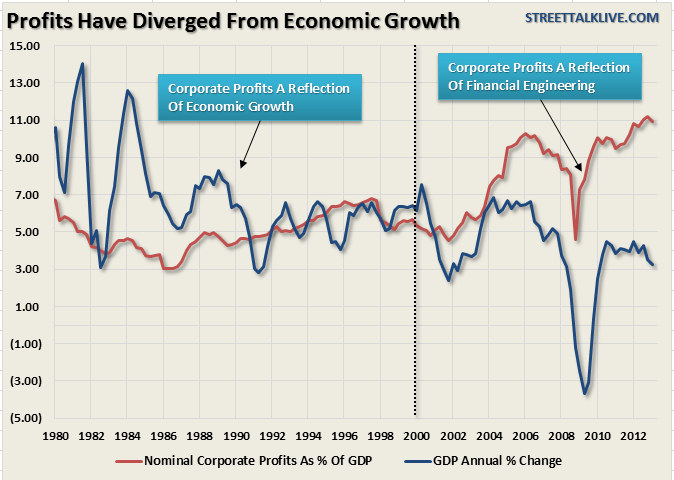
The reason why most Americans are not feeling the recovery trickle down to them is that the FIRE side of the economy is capturing a large share of the profits (more fuel for the growing income inequality trend).  Just take a look at how much of the recent growth has come courtesy of financial engineering:
Corporate-Profits-GDP-081613

Corporate profits as a percent of GDP are at generation high levels.  Yet GDP growth is weak (especially if you consider how much growth is coming from FIRE activity).  This is reflected in stagnant household income growth and the reality that wealth continues to shift into the hands of a very few Americans.

Redoing the last bubble

The problem with all of this is that we are simply redoing the last bubble.  This is a similar variation of our last bubble (i.e., financial sector deep into speculation, quickly rising real estate, no income growth, leveraging on debt, etc).  The finance and real estate side of the economy is driving profits and speculation, yet we see that for most Americans, the gains are simply not there.  This is just part of the financialization of our current system.  It is odd that big banks and firms are so interested in rental real estate yet they can extract money from Americans via this measure because the Fed is basically offering zero percent rates to member banks.  In other words, it is a riskless trade so why not grab all the real assets you can while the Fed continues to devalue the purchasing power of Americans?

The FIRE economy is back in a big way.  Of course you shouldn’t be surprised that this isn’t helping most Americans prosper.

Saturday, August 18, 2012

Wall St. spent $4.2 billion lobbying since '06


More precisely, the entire Finance Insurance and Real Estate (FIRE) sector spent that money lobbying, of which $879 million went directly to politicians' campaigns. That comes to $1,331 per minute spent influencing our elected leaders.  

How do you think your influence stacks up against theirs?  And remember, these titans of finance are the greediest and supposedly the smartest guys in America; if they spend that much money it means they think they'll get a good return on their investment.

You can use this Legislative Scorecard from Elect Democracy to see how much your Congressmen took from FIRE, and how loyal they were to FIRE in voting.  I can see, for example, that Rep. Geoff Davis [R-KY] took $1.6 million from FIRE and has a loyalty rating of 86 percent.  And KY Sen. Rand Paul [R-KY], who hasn't been in office long and has taken only $66,000, nevertheless has a 100 percent loyalty rating.  But nobody tops Sen. Majority Leader Mitch McConnell, who took $6.2 million from FIRE since 2006... and of course displayed 100 percent loyalty.  

Actually, that's not entirely true: President Barack Obama received $44 million from FIRE since 2006.  Gee, I wonder where his loyalty is?


Thursday, May 10, 2012

Taibbi: How Wall St. killed Dodd-Frank after it passed

Concludes Taibbi, sadly:

But money never gets tired.  It never gets frustrated. And it thinks that drilling holes in Dodd-Frank is every bit as interesting as The Book of Mormon or Kate Upton naked. The system has become too complex for flesh-and-blood people, who make the mistake of thinking that passing a new law means the end of the discussion, when it's really just the beginning of a war.


It's bad enough that the banks strangled the Dodd-Frank law. Even worse is the way they did it - with a big assist Congress and the White House.
By Matt Taibbi
May 10, 2012 | Rolling Stone

Thursday, February 10, 2011

MB360: FIRE burning down U.S. middle class

Financialization Era – how banking welfare captured our economy and ravaged the wealth of the working and middle class. Building profits through financial debt leverage.

By mybudget360 February 10, 2011

The American banking system has transformed the economy into one enormous speculative casino with bells and whistles and free cocktails for those that participate. The problem of course is that most don't have excess income to drop into the financial slot machines. Now banking in better times should be seen as the lubricant of the economy. It allocates capital to areas in the economy where actual real growth was occurring. Today the financial sector operates as an incestuous industry funding growth in its own industry. A snake swallowing its own tail but when the inevitable end comes, it is society that is forced to pick up the tab. Ultimately profits have to come from something real and not just skimming imaginary profits from interest. This banking welfare is largely a reason why our economy is faltering on the vine and Wall Street banking profits are soaring. It is no coincidence that as debt pilfered the economy that financial profits soared. We are living in era that can be dubbed the financialization of the American economy.

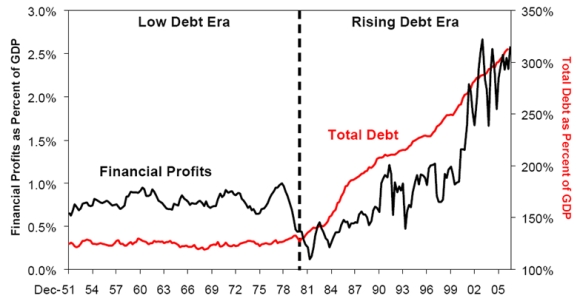
Debt leverage and banking profits go hand in hand

financial profits as a share of debt


Source: Peak Watch

The above chart really highlights the destruction of our economy in a rising debt era. In a low debt era financial profits were held in check from the 1950s to the early 1980s. Financial profits as a share of GDP hovered around one percent. That all changed in the 1980s and finally reached an apex in our Great Recession. The financial sector grew its profit margins at a time where more Americans were borrowing and going into debt to finance a lifestyle that was setup for a solid middle class. Yet the middle class was not there and many used debt to play a game of pretend for a few decades. All this was playing out during a time when the top 1 percent that were heavily vested in the banking sector were usurping wealth from the real economy.

It is no coincidence that during this time our workforce has shifted from manufacturing to finance:

fire-economy


Source: Macromon

We have done a complete 180 turn here. In 1947 the manufacturing sector contributed 25.6 percent to our entire GDP base while the FIRE sector made up 10.5 percent. In 2009 FIRE makes up 21.5 percent while manufacturing is down to 11.2 percent. Given the massive fraud, corruption, scandalous rent seeking behavior, and graft why should we be happy with all the bailouts given to this sector? The financial industry has largely become one giant casino and the stock market no longer reflects the health of the US economy. Most banking profits are now being made overseas as this nation's bailouts are going to global banks that are now fueling the growth and speculation abroad. This is what Americans get in exchange for trillions of dollars of bailouts to what are largely legalized loan sharks.

To further highlight how the financialization of America has harmed the economy we need only look at the stagnant wages of American families. 2000 to 2010 was the first decade where the median household income fell since the Great Depression era of the 1930s. This all happened during a time of unrestrained financial speculation and growth. What happened in the 1920s? Rampant financial fraud by banks so it is no surprise that we ended up in the same place. The only difference today is that after the crash nothing has changed. We still have the same financial sector in full operation. Half of American workers make $25,000 a year or less. This is such an important point because it demonstrates how the quality of life for many has gone negative in the last ten years. On this path the financialization of the country will continue to throw more off the middle class pedestal (or at least what remains of it).

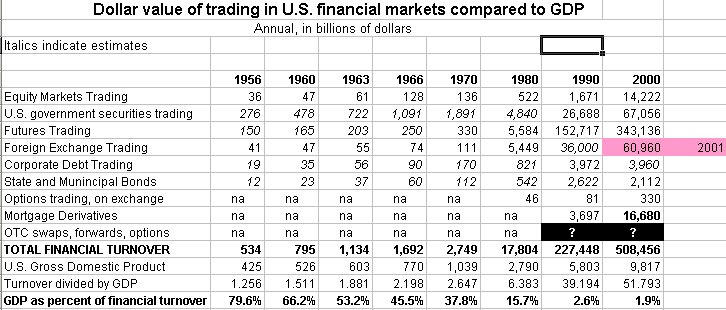
To further demonstrate the casino like nature of our stock markets just look at the actual trading volume for various markets over the last 60 years:

Financial_Turnover


Source: BIS, Wikipedia

This is a fascinating look at how much stock markets have become like casinos.

"In 1956 for example total dollar volume traded on various markets amounted to $534 billion. At the same time US GDP was $425 billion. Most of the trading occurred in boring and safe government securities. Fast forward to 2000. $508 trillion is traded and US GDP is only $9.8 trillion!"

What is even more insane is the amount being traded on the foreign exchange markets. $343 trillion was traded when global GDP is roughly $54 trillion. How can this be? The global stock markets are largely vacuums sucking the life and productivity from working class people all over the place. Investment banks make their profits as rent seekers and leech onto productive sectors of the economy that actually make things.

The financialization of our country has led us to a situation where bailouts are handed out to investment banks without any oversight because so much wealth is aggregated in these few hands. These industries have bought out our government and have laws and regulations that are stripped down to the point where all the above is allowed. Maximum leverage and if things go bust the taxpayer will be forced by their bought out politicians to bailout these sectors. Since the debt needs to be repaid, many in their local communities are witnessing rising taxes and cuts to local services. This happens under the guise that people need to tighten up their belt. Of course this happens at a time when global trading markets are leveraging their volume tenfold the amount of global GDP. Don't be fooled, the real culprits here are the banks and the financial sector. There is graft in many areas of the economy but this is the nucleus of the mess. If things keep going forward in this financialization phase there will be no middle class in the US in 10 to 20 years.